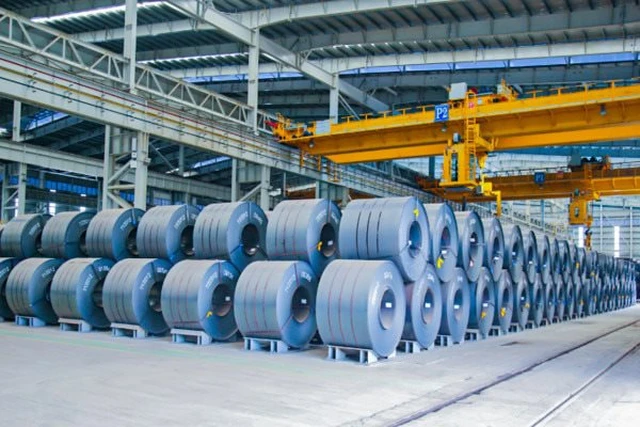
(HSV VIETNAM GROUP) - Since the bottom in April 2025, a series of stocks such as HPG, TVN, NKG, HSG, TLH,... have increased dozens of percent in value.
Facing high selling pressure and overwhelming almost the entire trading time, VN-Index suddenly narrowed the decline to 1 point at the end of the session on September 3.
In that context, steel stocks became the focus as they raced "green and purple". Nam Kim Steel (code: NKG) and Hoa Sen (code: HSG) "joined hands" to hit the ceiling, contributing to helping the main index reduce its sharp decline. Liquidity on these two stocks also increased dramatically, trading volume at NKG and HSG reached 32 million units and 23.5 million units, respectively.
Besides, other codes such as TVN, TLH, TDS or HPG,... all witnessed positive increases from nearly 3% to 5% in value.
Since the bottom of April 2025, a series of stocks such as HPG, TVN, NKG, HSG, TLH,... have increased dozens of percent in value.
The steel group's upward momentum is reinforced by many positive information. In the region, the downward price pressure from Chinese steel has cooled thanks to the Chinese Government's drastic measures to cut production. In July, production output in this country decreased by 4% over the same period and since the beginning of the year, output has decreased by 3%.
The cooling of Chinese steel has become one of the important driving forces driving the domestic steel industry. Along with that, the second half of the year is the peak consumption period when real estate supply improves and public investment disbursement is boosted, creating even more expectations for the recovery of the entire industry.
Updating data in the first 7 months of the year, domestic steel consumption grew by 16% over the same period. More specifically, consumption of construction steel and HRC increased by 14% and 26% respectively thanks to gaining market share from Chinese steel. Particularly, construction steel and HRC prices have shown signs of recovery since July by about 3% and 4% compared to the previous month to 560/530 USD/ton.
In the latest steel report, MB Securities (MBS) expects coal and ore raw material prices to cool down in the context of oversupply in Australia and Brazil when these countries boost mining output thanks to favorable weather. More specifically, in the period 2025 - 2026, coal supply is forecast to grow by 1.5%/2% over the same period and ore will remain at a high level with an expected increase of 2%/3%. In addition, the decline in demand for input materials comes from China's move to cut steel output.
"When steel prices are positive and raw materials such as coal and ore decline, the gross profit margin of manufacturing enterprises such as HPG is forecast to continue to increase by 1.1 and 0.2 percentage points in the period 2025 - 2026," the report stated.
For galvanized steel companies such as HSG, NKG and GDA, HRC prices have tended to recover since the end of Q3/25, so galvanized steel selling prices will benefit due to being anchored to HRC prices. In addition, stockpiling cheap HRC inventory will help galvanized steel sheet companies increase their gross profit margin by about 0.7 - 1 percentage point in 2025 - 2026. Taken together, the industry's gross profit margin is forecast to increase by 1 and 0.5 percentage points in the period 2025-26.
Thanks to the motivation coming from growing consumption output ahead of domestic demand and recovering gross profit margin, MBS forecasts that the entire steel industry's profit in 2025 and 2026 could grow by 47% and 32% respectively over the same period.
MBS said that the P/B of steel industry enterprises is highly correlated with the steel price cycle. In the period 2020 - 2021, in the context of construction steel and HRC prices increasing by 120% and 118%, the PB valuation level of businesses in the industry has increased from 0.4 - 1.0 to 1.1 - 3.2 thanks to the positive impact of steel prices on gross margin and profit growth. Therefore, during the period of increasing steel prices, the PB of steel industry enterprises is expected to improve sharply compared to the period of flat steel prices.
"Steel prices in the period 2025 - 26 have begun to pass the bottom and mark the starting point for a new cycle of increase in steel prices in the context of strong domestic demand growth," MBS analysis team assessed.
Thanks to that, MBS expects the P/B valuation of companies in the industry to increase to 1.4 - 2.8 (about 30% higher than today). Enterprises such as Hoa Phat (HPG), Hoa Sen (HSG) and VG Pipe (VGS) are evaluated positively.
Ha Diem HSV