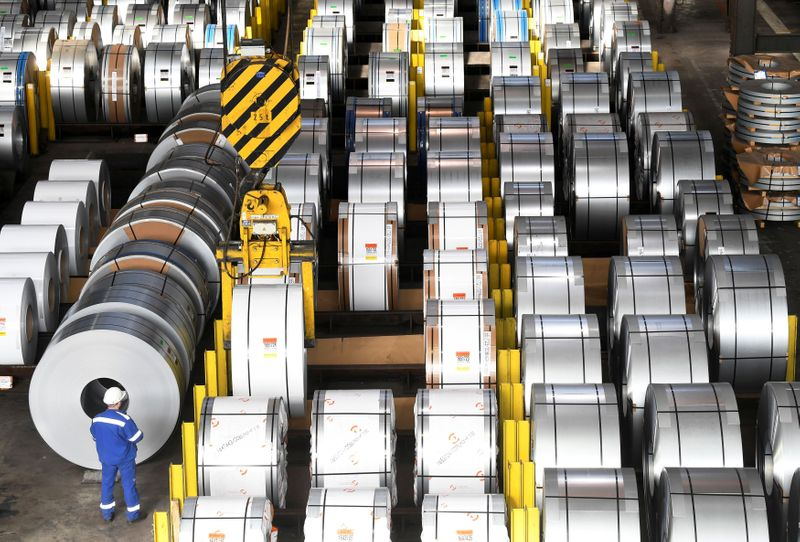
HSV VIETNAM GROUP) – Iron ore futures rose but stuck in a narrow range as traders weighed the resumption of production by some steelmakers in top consumer China in the face of high port inventories and the prospect of crude steel output cuts.
The most traded September iron ore contract on the Greater China Commodity Exchange increased 0.6% to 832.5 CNY (equivalent to 114.67 USD)/ton.
Benchmark iron ore price for July delivery on the Singapore Exchange increased 0.89% to 108.25 USD/ton, partly supported by the weakening USD.
Some plants have restarted blast furnaces under maintenance, supporting iron ore demand, analysts at Sinosteel Futures said.
Analysts at Maike Futures said steel profit margins improved somewhat after steelmakers reduced coking coal purchasing prices, creating an opportunity for iron ore prices to rise.
China kept its benchmark lending rate unchanged at a set monthly level, despite a series of recent data suggesting more support is needed to underpin an uneven economic recovery.
Market participants in China are currently looking for direction from the Third Plenum, a key meeting of the Central Committee of the Communist Party of China to be held in July 2024. The plenum is expected to focus on deepening reform and promoting China's modernization process.
Other steelmaking components on the DCE lost ground, with coke and coking coal prices down 0.93% and 0.68%, respectively.
Steel benchmarks on the Shanghai Futures Exchange are uneven. Rebar prices decreased by 0.19%, rolled steel prices decreased by 0.11%, while steel bar prices increased by 0.1% and stainless steel prices increased by 0.61%.
Analysts at Everbright Futures said that downstream steel consumption has clearly decreased due to high temperatures and heavy rains occurring in many areas; Steel traders take a cautious stance, focusing on reducing inventories.
Ha Diem HSV