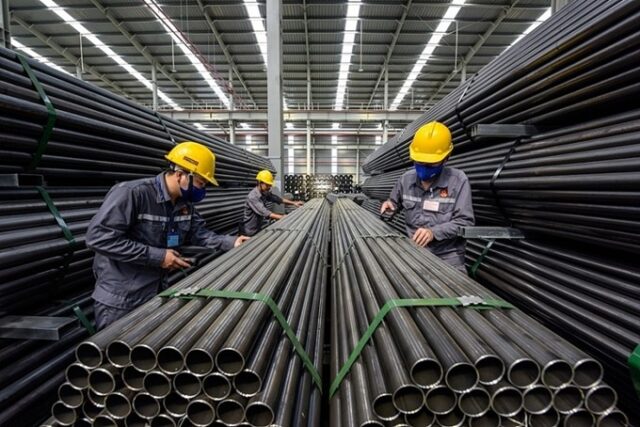
Hanoi Iron and Steel (HSV) - From May 11 until now, steel prices have decreased 8 times in a row with a total decrease of up to 3 million VND.
On July 9, many steel enterprises continued to lower product prices by up to 300,000 VND/ton. This adjustment is the 8th consecutive decrease since May 11.
In the Northern region, Hoa Phat adjusted a reduction of 360,000 VND/ton and 200,000 VND/ton for CB240 rolled steel and D10 CB300 rebar steel. After adjustment, the price of these two types is 16.24 million VND/ton and 16.6 million VND/ton.
Hoa Phat steel price developments until July 10. Source: Steel Online
With Vietnam Italy steel, CB240 and D10 CB300 decreased by 200,000 VND/ton and 210,000 VND/ton to 16.16 million VND/ton and 16.56 million VND/ton, respectively. Regarding Viet Duc steel, the above two types of steel decreased by 300,000 VND/ton and 190,000 VND/ton, respectively, to 16.06 million VND/ton and 16.51 million VND/ton. With Kyoei steel, today's price is 16.06 million VND/ton and 16.46 million VND/ton for CB240 and D10 CB300 after decreasing 200,000 VND/ton and 140,000 VND/ton respectively.
Thus, in 2 months, steel prices recorded the 8th decrease with a total decrease of more than 3 million VND/ton, depending on the brand and type of steel.
Why do steel prices continuously decrease?
According to the explanation of the Vietnam Steel Association, in the first months of 2022, Vietnam's economy will recover. However, demand for steel in construction projects is not high, so steel consumption has decreased. Weak demand pressure in the Chinese and global markets led to a decrease in trading prices of steel products.
In addition, raw material prices have decreased continuously since the end of April, causing the market to slow down. On June 7, the price of steel billet traded in Southeast Asia was at 649 USD/ton, down 163 USD/ton compared to early May. Faced with reduced demand, distributors sought to reduce inventory, only buying the type and amount needed to meet customer demand, pulling domestic steel consumption down.
According to a report by SSI Research, domestic steel demand decreased by about 6% over the same period in the first 5 months of the year. After increasing by 15% in the first quarter due to pent-up demand, domestic consumption of finished steel products (including construction steel, galvanized steel and steel pipes) in April and May decreased by about 32% over the same period.
SSI Research experts believe that the significantly weaker demand may be due to a combination of three factors: high steel prices, along with the increase in other construction material costs, causing construction activities to stagnate. In addition, concerns about steel prices peaking have caused distributors to temporarily stop stockpiling inventory. Tighter management policies on capital flows into the real estate sector also affect steel demand and steel prices.
The process of reducing steel prices may be lengthy
Construction steel prices in Vietnam have decreased by about 11% compared to the peak in March, while hot-rolled coil (HRC) prices have also decreased by 25% compared to the peak in early April, according to developments in world steel prices, SSI Research cited data.
After increasing 56% when the Russia-Ukraine conflict began, HRC steel prices in the EU have now adjusted about 35% below the level before tensions occurred. HRC prices in China and the US have also decreased by 15-20% in the past 3 months due to less construction and production activities, amid inflation worldwide and especially due to weak demand in China due to social distancing, adverse weather and slowing real estate market growth due to rising interest rates.
In terms of supply, global steel output overall fell in the first half of the year, with total production output estimated to fall 6.3% year-on-year in the first five months of the year. However, on a monthly basis, steel production in China has gradually increased over the past 3 months, increasing inventories at factories and creating more pressure on steel price movements in the region.
SSI Research points out that coking coal prices have dropped 36% from their peak in March, while iron ore prices have also dropped 13% in the past 3 months due to reduced steel production (especially from China). Although lower raw material prices may lead to companies having to set aside inventory provisions in the short term, cheaper raw materials may help reduce companies' production costs in the coming quarters.
Because the profit margins of Chinese companies have decreased to a minimum level, steel prices in the near future will be unlikely to decrease at a strong rate as in recent months. However, the recovery in steel prices is also relatively limited due to weak demand until China fully opens its economy.
According to VNDirect's strategy report for the last 6 months of the year, the total investment of key transportation projects in Vietnam amounts to 32.1 billion USD in the period 2022-30. For the whole year of 2022, VNDirect's experts still maintain the expectation that realized public investment capital will increase by 20-30% over the same period when growth in the second half of 2022 will be higher than the first half of the year thanks to the low base level of the same period in 2021. With Vietnam still gradually reopening the economy after the epidemic, VNDirect expects public investment disbursement to grow in the construction and building materials industry.
VNDirect's report says that promoting infrastructure development and the warming of the residential real estate market will help Vietnam's construction steel consumption increase by 5% in 2022 and 15% in 2023, respectively.
VNDirect expects construction steel prices to gradually decrease to the average level in the long term, however, the prospect of steel demand recovering strongly after the pandemic and input raw material prices remaining at high levels will make this price reduction process last longer than expected. CTCK believes that domestic construction steel prices will increase 1% over the same period in 2022 before decreasing 10% over the same period in 2023.
Exports will decelerate until the end of the year
According to SSI Research, exports remained stable in the second quarter of this year, but may decelerate in the coming quarters. Export output of finished steel products will increase by 13% in the first 5 months of 2022.
However, the export channel still tends to slow down in recent months, especially in the galvanized steel segment, with monthly output about 30% lower than the peak in April 2021. Such a decline in output is due to reduced demand in key export markets (especially the US and EU), which under favorable conditions once accounted for 60-70% of Vietnam's galvanized steel export output. Galvanized steel companies such as Hoa Sen and Nam Kim Steel have received export orders until the end of July and August with an output of about 60,000 tons/month. However, the fact that export orders are placed 1 to 2 months in advance shows a slowing trend compared to the period when companies signed about 3-4 months in advance.
Also according to SSI Research, exports in the second half of the year may be negatively affected by protectionist measures imposed by the EU. The EU has added Vietnam to the group of "other countries" with an import quota for this group of 2.1 million tons of hot-dip galvanized steel (HDG) from July 1, 2021 to June 30, and increasing by 4%/year in the next two years. According to the EU, Vietnam's HDG export output to Europe is estimated to reach 979,000 tons in 2021. With this adjustment, exports from Vietnam to the EU may decrease in the near future. However, the contribution from the EU market to Vietnam's steel exports has also decreased compared to the previous period due to a significant decrease in EU steel prices in recent months.