(HSV VIETNAM GROUP) – Construction steel consumption in October increased sharply by 44% over the same period last year to 1.25 million tons. This consumption level is even higher than in October 2021 - the peak period of the steel industry. The steel market is expected to be more vibrant in the fourth quarter thanks to the acceleration of construction projects.
The market recovered, construction steel was the bright spot
According to data from the Vietnam Steel Association (VSA), the output of finished steel products of all kinds in October reached 2.6 million tons, up 9% over the same period last year.
Sales volume reached 2.7 million tons, up 23% over the same period last year. Sales are 100,000 tons higher than production, and the growth rate is also higher, showing positive signs for a long-term gloomy industry.
According to VSA, in October, the domestic steel market recorded positive impacts from the demand for galvanized steel and construction steel to re-roof houses and repair damaged structures from storm Yagi and some storms in the Central region in September.
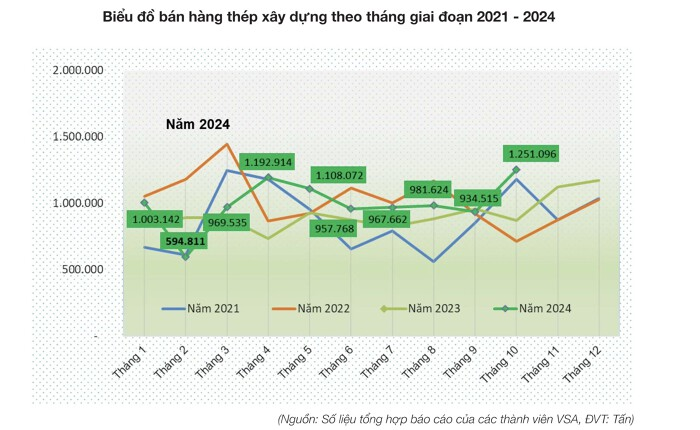
In particular, construction steel consumption (accounting for about 45% of the proportion of steel products) is a bright spot when it increased sharply by 44% over the same period last year to 1.25 million tons. This consumption level is even higher than in October 2021 - the peak period of the steel industry.
VSA said that the amount of construction steel consumed in October was mainly supplied to construction projects, and the civil segment was still at a low level.
Similarly, consumption of cold rolled steel, galvanized steel, and steel pipes all grew by double digits 30 - 55% over the same period last year. Hot rolled coil (HRC) is the only product bucking the trend with a decrease of 27% over the same period last year. Of which, exports decreased by more than half.
Overall for 10 months, steel sales of all types reached 24.4 million tons, up 15% over the same period last year.
The recovery of the steel industry takes place in the context of the Ministry of Industry and Trade recently introducing a series of trade defense measures.
Most recently, on October 24, the Ministry of Industry and Trade extended for another 5 years the application of anti-dumping measures on color-coated steel products imported from China and Korea (from October 24, 2024 to October 23, 2029). The highest tax rate for Chinese companies is 34.27% and for Korean companies is 19.25%.
Previously, this case was initiated into investigation in 2018. On October 24, 2019, the Ministry of Industry and Trade imposed anti-dumping tax on color-coated steel sheets from China and Korea.
In a related move, in June, the Ministry of Industry and Trade investigated anti-dumping on a number of galvanized steel products originating from China and Korea (Case code AD19).
The period of investigating dumping behavior and determining damage is from April 1, 2023 to March 31, 2023.
The party requesting the investigation is 5 businesses including Hoa Sen, Nam Kim, Phuong Nam Ton, Dong A Ton, China Steel & Nippon Steel Vietnam.
These businesses have provided evidence of dumping behavior and requested investigation, determining the dumping margin for imported goods from China is 69.23% and Korea is 3.41%.
At the end of July, the Ministry of Industry and Trade decided to investigate and apply trade defense measures on hot rolled coil (HRC) steel imported from China and India.
The investigation period to determine dumping and damage is from July 1, 2023 to June 30, 2024.
The Ministry of Industry and Trade said that the party requesting the investigation has provided evidence to prove the dumping of goods, determining the dumping margin of HRC imported from India and China at 27.83%.
The market becomes more vibrant in the fourth quarter and recovers in 2025
With the current situation, VSA forecasts that in the remaining months of 2024, the Government's policies to support reconstruction and post-storm recovery will impact steel demand. The fourth quarter is also the appropriate time to deploy and accelerate the progress of construction projects. At the same time, the construction steel market is also expected to become more vibrant.
"For the whole year 2024, production and sales of steel products can achieve growth compared to the same period in 2023," VSA said.
In a recent report, Vietnam Steel Corporation (VNSTEEL) also expected the domestic market to be more vibrant in the last months of the year. However, this business also believes that the domestic steel market still has many potential challenges due to the general impact of the world steel market and domestic demand has not really recovered.
The world economy continues to face many worrying issues such as inflation, tightened monetary policy, geopolitical instability... In particular, the slow recovery of China's real estate market has a great impact on domestic demand, forcing the country to continue increasing steel exports, creating great competitive pressure on markets in Southeast Asia, including Vietnam.
In terms of longer prospects, talking to us on the sidelines of the 2025 Investment Forum organized by VietnamBiz, Mr. Dao Minh Chau, Deputy Director of Stock Analysis at SSI Research, said that next year the steel industry will benefit from the recovery cycle of the real estate industry and promote public investment. The recovery momentum of this steel market may last for the next 2 - 3 years.
However, Mr. Chau believes that steel prices are unlikely to return to an upward trend because they still depend on developments in the Chinese market. In the past, the cycle of falling steel prices in Vietnam and the world only lasted about 2 years, but this cycle has lasted up to 3 years. In the Chinese market, China's steel demand is forecast to remain at a low level, about 900 million tons.
“This affects the difficulty of steel prices recovering strongly. However, it is difficult for prices to decrease deeply because China's capacity has also decreased quite a lot. Besides, there is still a price support factor related to China's economic support measures. If trade tensions arise with the US, China may have a stimulus package for the domestic economy," Mr. Chau said.
Ha Diem HSV